Imported goods in a bonded warehouse can be stored with duty and import VAT on hold until they are sold in the UK or exported.
Key takeaway
A bonded warehouse is a place approved by HMRC where imported goods can be stored with customs duty and import VAT suspended. Duty is paid only when goods are released for sale in the UK, and no UK duty is paid on goods that are exported again. There is no time limit on how long goods can stay. HMRC calls this a customs warehouse.
If your business imports goods and holds them before selling, a bonded warehouse changes when you pay duty. Instead of paying at the port, you pay as stock leaves the warehouse for UK customers. Anything you send abroad leaves without UK duty at all.
Storing goods with duty on hold is a long established part of UK customs, used by importers of everything from clothing and homeware to timber, machinery and steel. Since 2021, customs declarations have become business as usual for UK importers, and their numbers keep growing. HMRC's latest figures show 334,294 businesses imported goods in 2025, 4% more than the year before, and the number importing only from outside the EU rose by 12%. As more businesses buy from further afield, planning when duty is paid has become a normal part of managing imported stock.
This guide explains what a bonded warehouse is, how it works under HMRC rules, and how to tell whether one would suit your business.
1. What does bonded warehouse mean?
"Bonded" refers to the guarantee, or bond, that traditionally covered the duty owed on goods held under customs control. Goods stored this way are said to be "in bond". The meaning today is simple: the goods are in the UK, but import duty and import VAT have not yet been charged.
In UK law and on GOV.UK, the official name is customs warehousing. It is one of the customs special procedures, alongside inward processing and temporary admission. Bonded warehouse and customs warehouse describe the same thing.
One exception: alcohol and tobacco are stored under a separate regime called excise warehousing, which suspends excise duty. Section 8 explains the difference.
2. How does a bonded warehouse work?
- Goods are declared into customs warehousingInstead of releasing goods for sale in the UK at the border, they are declared to the customs warehousing procedure. No duty or import VAT is paid at this point.
- Goods arrive at the warehouseThey must reach the approved premises within 5 working days of customs clearance and be entered into the stock records.
- Goods are stored and recordedEvery movement in and out is tracked in records HMRC can check. Simple handling such as repacking, sorting, labelling and quality checks is allowed. Manufacturing or processing needs IPR instead.
- Goods leave, and only then is duty settledDuty is worked out at the rates in force on the day goods are released, and tariff preferences or quotas can be claimed at that point. Goods exported again leave without UK duty.
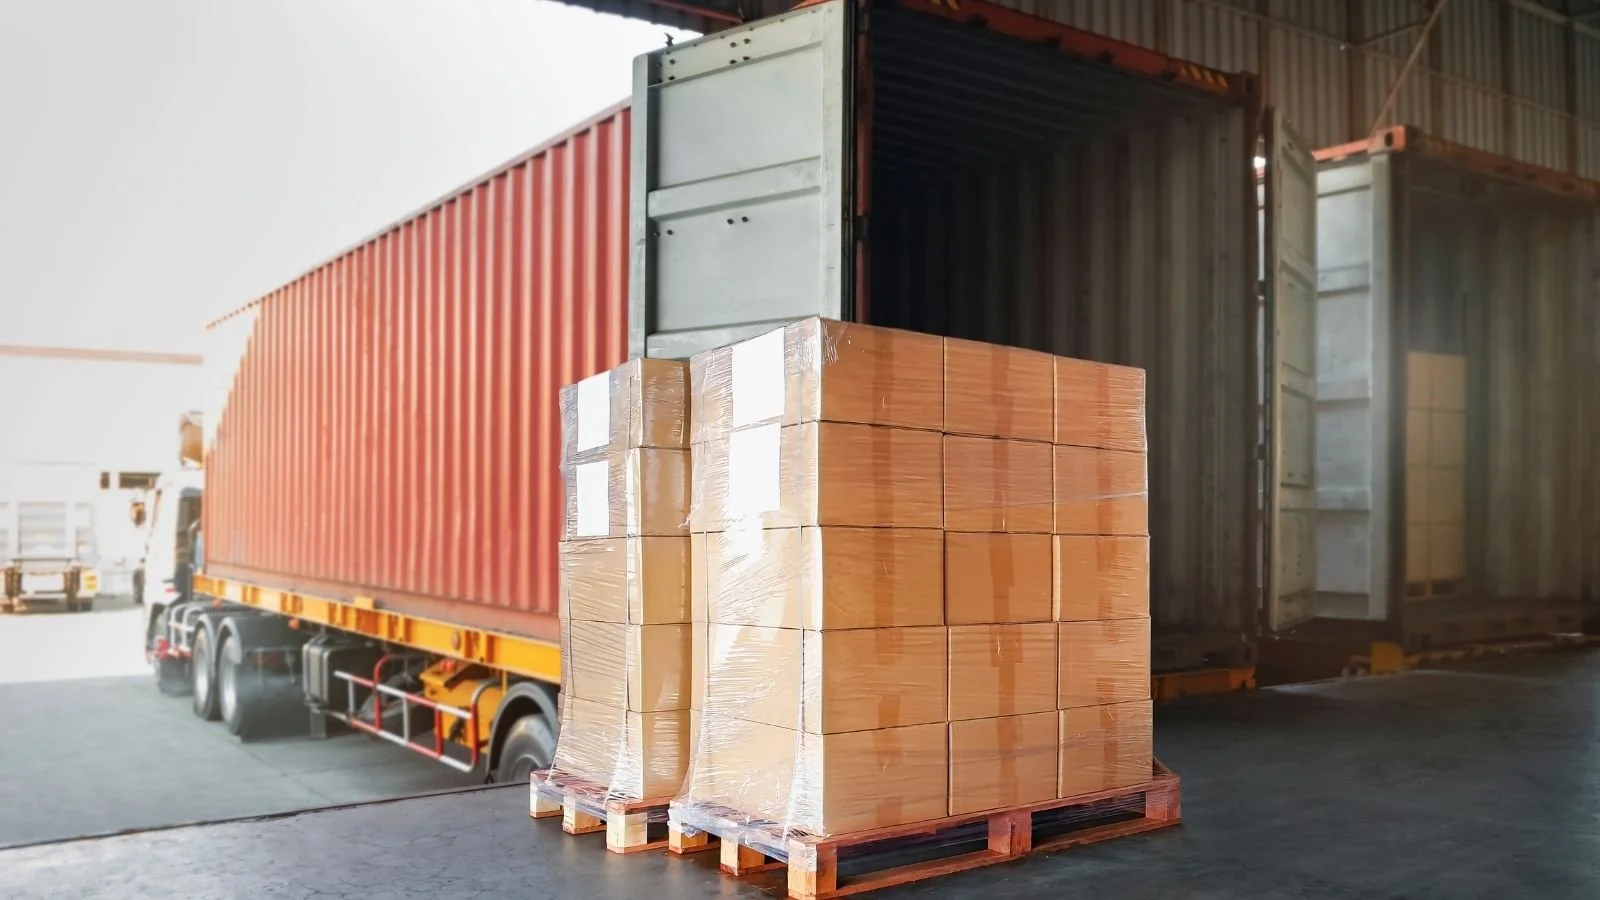
Goods must reach the bonded warehouse within 5 working days of customs clearance, and every movement is recorded from then on.
Four ways goods can leave
3. Public and private bonded warehouses
HMRC approves two types. The difference is whose goods are stored and who runs the site.
For a business storing its own goods.
- You run the warehouse and own the goods
- Approved at your own premises
- Full control of stock, records and timing
- Duty savings stay in your business
Run by a warehousekeeper for other businesses.
- The operator stores goods owned by others
- Needs letters of intent from future users to show demand
- You rely on a third party's records and processes
- Storage fees are paid to the operator
To place goods in a bonded warehouse, the owner of the goods (HMRC calls them the depositor) must be established in the UK. A business based overseas can still use one through a UK warehousekeeper or an indirect customs representative.
4. Bonded warehouse benefits
Better cash flow. Duty is paid as goods are sold, so cash is not tied up in stock still sitting in the warehouse.
No UK duty on goods you export. Stock sold to customers abroad leaves without UK duty, which otherwise could not be recovered.
No storage time limit. Seasonal stock, slow moving lines and bulk purchases can be held for as long as needed.
Sell goods while they are stored. Sales made while goods are in the warehouse are generally outside the scope of UK VAT, with the exception of retail sales.
Claim preferences on release. Tariff preferences and quotas can be claimed when goods are released, based on the rules in force on the day.
To see what this could mean for your own imports, try the bonded warehouse savings calculator.
5. How long can goods stay in a bonded warehouse?
There is no time limit. Goods can stay in a UK bonded warehouse for as long as needed. HMRC can only require goods to be removed in limited cases, such as where they pose a risk to people, animals, plants or the environment.
That makes a bonded warehouse useful for businesses that buy in bulk, hold seasonal stock, or sell some goods in the UK and some abroad.
A £15m clothing and homeware importer, approved for its own bonded warehouse in 3 months
They were paying around £97,000 a year in import duty at the port, including on stock later sold to customers in Ireland and the EU. Their stock failed an HMRC check at a third party warehouse. Three months later, their own bonded warehouse was approved with no findings.
If you're weighing up a bonded warehouse, they would be my first recommendation. Readyset knew exactly what was needed at each stage, so it never became a drain on our time.
Finance Director
UK clothing and homeware importer
6. How does VAT work in a bonded warehouse?
Import VAT is suspended along with duty while goods are stored. It becomes due when goods are released for sale in the UK. Goods exported again leave without UK import VAT.
Most VAT registered importers already account for import VAT through postponed VAT accounting, which avoids paying it upfront. For them, the main cash benefit of a bonded warehouse is usually on duty.
Goods can also be sold while they are stored. These sales are generally outside the scope of UK VAT until the goods are removed, except retail sales. Retail sales from a bonded warehouse are limited to certain buyers, such as travellers leaving the UK, diplomats and international organisations, and remote or online customers where goods are picked and sent to order.
7. Disadvantages and responsibilities
Every bonded warehouse comes with responsibilities. These are the points to plan for before you apply:
HMRC approval takes time. The application, premises and records are all checked before approval.
Records must be accurate. Stock records must show every movement in and out, and HMRC can audit them at any time.
A guarantee may be needed. HMRC can ask for a guarantee to cover the duty on stored goods. It is not needed for AEOs or businesses that meet the AEO conditions.
Losses can still cost duty. Goods destroyed or lost through unavoidable causes, such as natural wastage, are not charged duty. Goods that go missing or are stolen are.
Handling is limited. Only simple handling is allowed. Any processing or manufacturing needs a separate IPR authorisation.
None of these are reasons to avoid a bonded warehouse. They are the reasons good preparation matters. Our guide on how to set up a bonded warehouse in the UK walks through the HMRC process step by step.
8. Bonded warehouse vs other options
Bonded vs non bonded warehouse
| Bonded warehouse | Non bonded warehouse | |
|---|---|---|
| When duty is paid | When goods are released for sale in the UK | At the port, before goods arrive |
| Goods exported again | No UK duty | Duty already paid and usually not recoverable |
| Time limit | None | None |
| HMRC approval | Needed | Not needed |
| Records | Detailed stock records HMRC can audit | Normal business records |
Bonded warehouse vs Freeport, excise warehouse and IPR
| What it is for | Where it applies | |
|---|---|---|
| Bonded (customs) warehouse | Storing imported goods with duty and import VAT on hold | Any HMRC approved premises, including your own |
| Freeport customs site | Storing and processing goods with duty, import VAT and trade measures on hold | Only inside a designated Freeport customs site, run by a Customs Site Operator |
| Excise warehouse | Holding alcohol and tobacco with excise duty on hold | HMRC approved excise premises |
| IPR | Processing or repairing imported goods with duty on hold | Wherever the processing happens |
Customs warehousing and IPR are often used together. For a closer look, read customs warehousing vs IPR.
9. Who uses a bonded warehouse?
Any business that imports goods and stores them before selling can benefit. There is no minimum import volume. It tends to pay off fastest for businesses that:
Import consumer goods such as clothing, homeware, toys and electronics for UK retail and ecommerce
Sell part of their imported stock to customers outside the UK
Buy in bulk or hold seasonal stock for months at a time
Import goods with higher duty rates, such as some steel, timber products and machinery
Our recommendation
If you hold imported stock for more than a few weeks, or export any of it, a private bonded warehouse at your own site is usually worth exploring. Start with your import data from the last 12 months: how much duty you paid, and how much of that stock was later exported. That shows you the savings before you apply. Our free calculator gives you a first estimate in a minute.
Find out how much a bonded warehouse could save you. Readyset is a British customs consultancy working with importers across the UK and worldwide. We will work out what one could save from your own import data, free of charge and with no commitment.
Book a free consultationFrequently asked questions
What is a bonded warehouse in simple terms?
It is a warehouse approved by HMRC where imported goods can be stored without paying import duty or import VAT. You pay when goods are released for sale in the UK, and no UK duty is due on goods that are exported again.
Is a bonded warehouse the same as a customs warehouse?
Yes. Customs warehouse is the official term HMRC uses. Bonded warehouse is the more common name for the same thing. Alcohol and tobacco use a separate regime called excise warehousing.
How long can goods stay in a bonded warehouse?
There is no time limit in the UK. HMRC can only require goods to be removed in limited cases, such as a risk to people, animals, plants or the environment.
Do you pay VAT on goods in a bonded warehouse?
Not while they are stored. Import VAT is suspended and becomes due when goods are released for sale in the UK. Goods exported again leave without UK import VAT. Sales made while goods are in the warehouse are generally outside the scope of UK VAT, except retail sales.
Can you sell goods while they are in a bonded warehouse?
Yes. Goods can be sold while stored, and those sales are generally outside the scope of UK VAT until the goods are removed. Retail sales are only allowed to certain buyers, such as travellers leaving the UK, diplomats, and remote or online customers where goods are picked and sent to order.
What happens if goods are lost or stolen from a bonded warehouse?
Duty is due on goods that go missing or are stolen. Goods totally destroyed or lost through unavoidable causes, such as natural wastage, are not charged duty if you can prove the loss to HMRC.
Can goods be processed in a bonded warehouse?
Only simple handling is allowed, such as repacking, sorting, labelling and quality checks. Processing, repair or manufacturing needs an IPR authorisation.
Can a business outside the UK use a UK bonded warehouse?
Yes, but the owner of the goods must be established in the UK to place goods in the warehouse. A business based overseas can use a UK warehousekeeper or an indirect customs representative.
Do I need a guarantee for a bonded warehouse?
HMRC may ask for a guarantee to cover the duty on stored goods. It is not needed for Authorised Economic Operators or businesses that meet the AEO conditions. Read more about AEO status.
What is the difference between a bonded warehouse and a Freeport?
A bonded warehouse can be approved at your own premises anywhere in the UK. A Freeport customs site only exists inside a designated Freeport and is run by a Customs Site Operator. Both suspend duty and import VAT, and Freeport customs sites also allow processing.
How do I get a bonded warehouse approved?
You apply to HMRC for a customs warehousing authorisation, with details of your premises, records and procedures. Our guide on how to set up a bonded warehouse in the UK covers each step.
Sources (checked October 2026): GOV.UK, How to use a customs warehouse · HMRC, Special procedure: customs warehousing · HMRC, Discharge of the customs warehousing procedure · GOV.UK, Declaring goods and paying tax when using a Freeport customs site · HMRC, Customs importer and exporter population 2025